
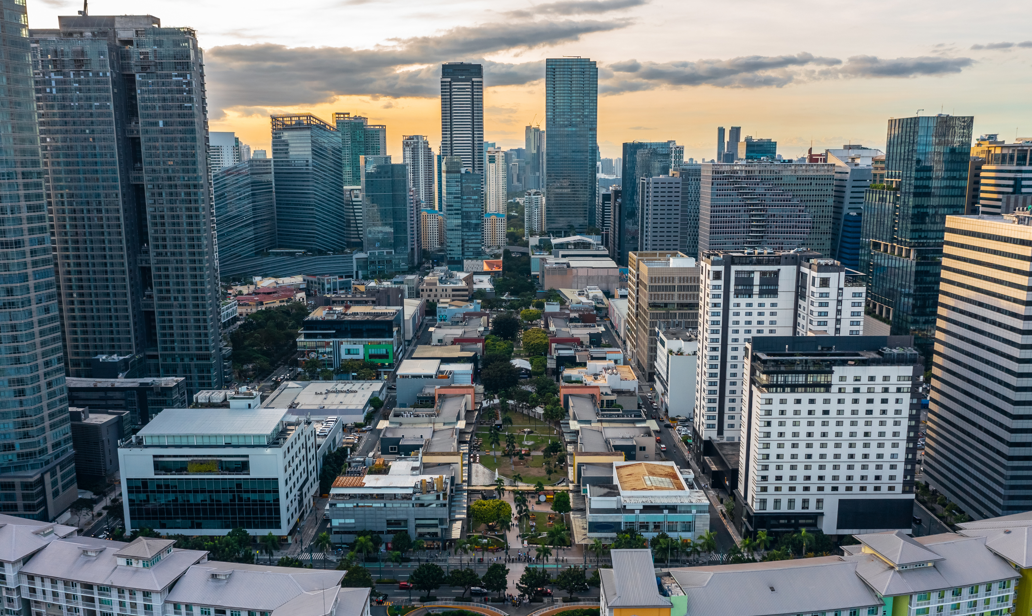
As the Philippine commercial real estate market heads into 2026, growth is no longer defined solely by traditional central business districts. A growing share of leasing activity, development interest, and investor attention is shifting toward secondary business districts across Metro Manila and nearby growth corridors. This decentralization marks one of the most significant structural changes shaping the market in the coming year.
Rather than signaling weakness in established CBDs, the rise of secondary districts reflects changing business priorities, improved infrastructure connectivity, and evolving workplace strategies. For companies, landlords, and investors, these areas are becoming central to long-term planning.
What Defines a Secondary Business District Today
Secondary business districts are areas outside the traditional CBDs that now support sustained commercial activity. These districts typically feature a mix of office buildings, retail components, residential developments, and access to major transport routes. While historically viewed as peripheral locations, many now function as independent commercial hubs.
In Metro Manila, districts such as Mandaluyong, San Juan, Parañaque, Las Piñas, Alabang, and parts of Quezon City are increasingly treated as viable alternatives to Makati and Bonifacio Global City. These locations benefit from established residential populations, improving infrastructure, and proximity to multiple employment centers.
What sets these districts apart is their ability to serve both business and workforce needs without the congestion and cost pressures associated with traditional CBDs.
Cost Efficiency Drives Location Strategy
One of the strongest drivers behind the shift toward secondary districts is cost efficiency. Office rental rates and overall occupancy costs remain significantly lower in many non-CBD locations. For companies managing headcount growth or restructuring post-pandemic space requirements, these cost differences are meaningful.
Lower rents allow businesses to lease higher quality space, invest in better layouts, or maintain satellite offices closer to where employees live. This has become especially relevant as companies adopt hybrid or flexible work models that prioritize accessibility over prestige addresses.
For landlords, competitive pricing has translated into stronger leasing activity and more stable demand, particularly from small to mid-sized enterprises and support operations of larger firms.




